When we started running a business in Vietnam, the difficult part was not one tax return. It was keeping several tax, payroll and labour deadlines visible at the same time. A founder does not need to prepare every form personally, but should know what may be due and what proof of submission should come back from the accountant.
This is the practical checklist we would want beside our own calendar. It covers a typical incorporated startup or small company in Vietnam, but not household businesses, listed companies, banks or every regulated industry.
Vietnam's new tax administration framework took effect on 1 July 2026 under the Law on Tax Administration 108/2025/QH15, Decree 252/2026/ND-CP and Circular 89/2026/TT-BTC. One practical change is that salary and wage PIT withholding returns are quarterly from that date, rather than monthly.
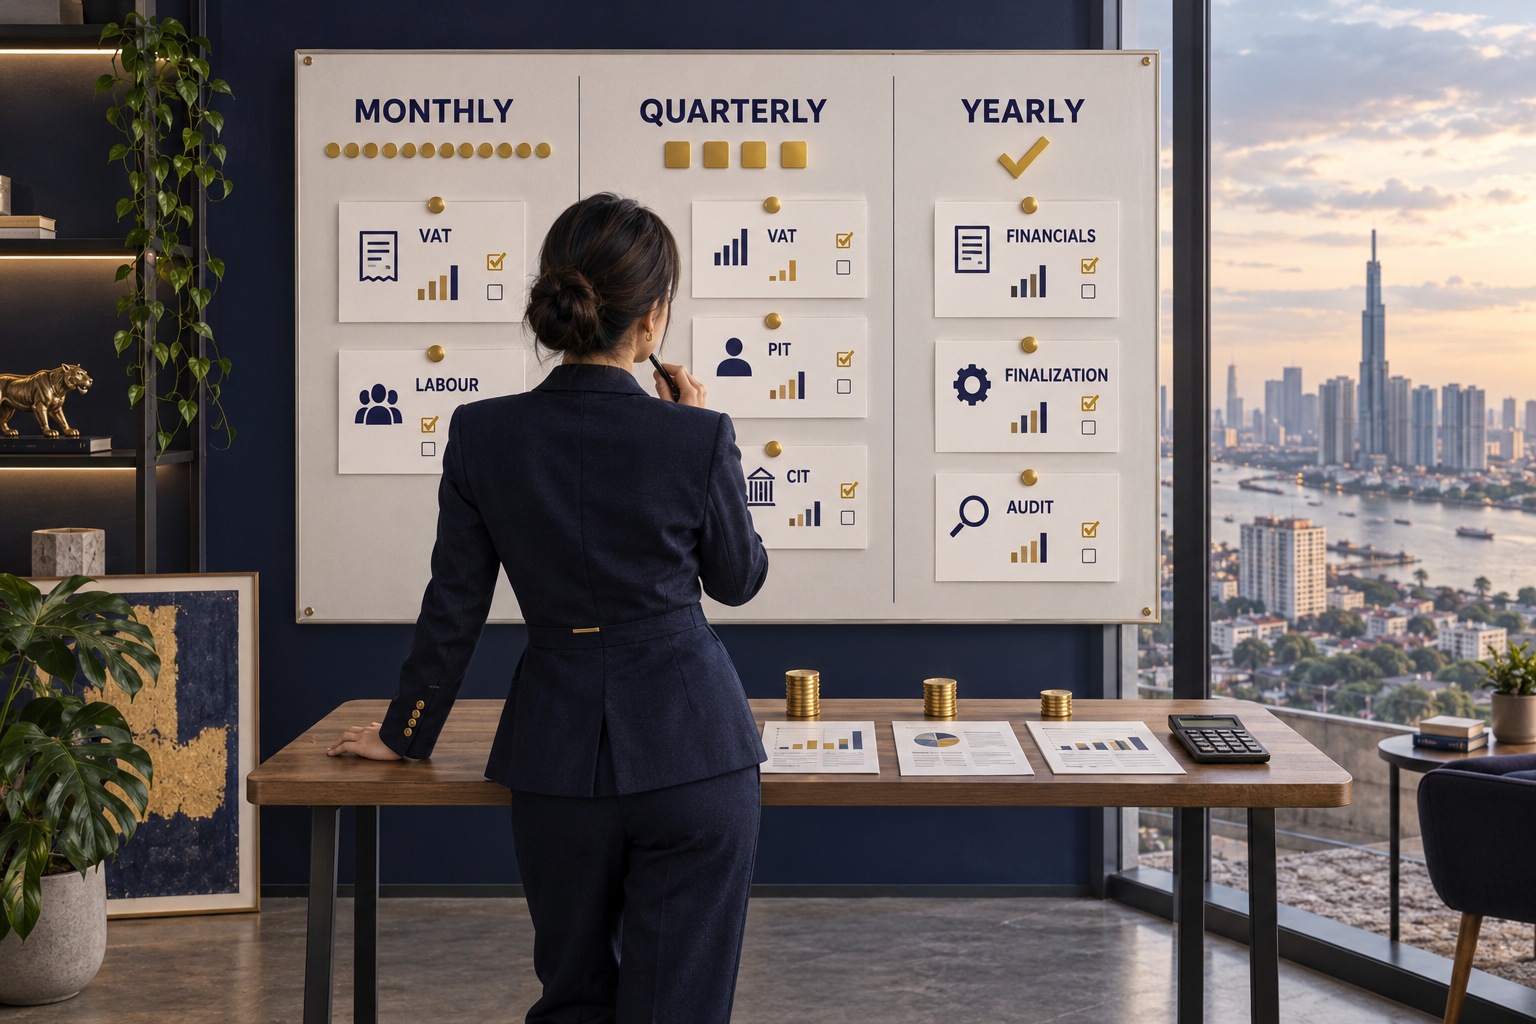
The compliance calendar at a glance
| Cycle | Main obligations | Standard deadline |
|---|
| Monthly | VAT for businesses with prior-year revenue above VND 50 billion | 20th of the following month |
| Quarterly | VAT for businesses with prior-year revenue of VND 50 billion or less; PIT withholding return if tax was withheld; provisional CIT payment | Last day of the first month after the quarter |
| Twice yearly | Report on labour use and changes | Before 5 June and before 5 December |
| Annually | Financial statements, CIT finalization and annual PIT finalization by the company; audit report if required | Normally by the last day of the third month after year-end |
| When triggered | Notice when the workforce increases or decreases by at least 50 employees | No fixed calendar date; submit promptly |
Set internal cutoffs seven to ten days earlier. If a deadline falls on a public holiday or non-working day, it generally moves to the next working day, but confirm the live filing calendar.
1. Value Added Tax return
- Definition: The VAT return, or tờ khai thuế GTGT, reports output VAT, eligible input VAT and the resulting tax payable, credit or refund position.
- Frequency: Monthly and quarterly are the two standard cycles. In general, a business with prior-year revenue of VND 50 billion or less files quarterly, while a business above VND 50 billion files monthly. A nil return may still be required unless a specific exception applies.
- Deadline: Monthly returns are due by the 20th of the following month. Quarterly returns are due by the last day of the first month after the quarter.
- Files to submit: Electronic Form 01/GTGT for the credit method or Form 04/GTGT for the direct-on-revenue method, plus any required schedules.
- Owner check: Reconcile e-invoices, purchase invoices, bank receipts and contracts before filing.
2. Personal Income Tax withholding return
- Definition: The PIT withholding return, or tờ khai thuế TNCN, reports tax withheld from salaries and wages paid to employees and other individuals.
- Frequency: Quarterly from 1 July 2026. No periodic return is required for a quarter in which no PIT was withheld, although payroll records must still be retained.
- Deadline: The last day of the first month after the quarter.
- Files to submit: Electronic Form 05/KK-TNCN and Form 05-1/PBT-KK-TNCN if tax allocation is required.
- Owner check: Match salaries, taxable benefits, deductions and withholding to contracts, payroll and bank payments. Review foreign employees and cross-border remuneration early.
Quarterly withholding is only part of the payroll tax cycle. For employee authorization, direct filing and common year-end issues, read our practical guide to personal income tax finalization in Vietnam.
3. Six-month and annual report on labour use
- Definition: The báo cáo tình hình thay đổi về lao động provides a structured employee snapshot to the labour and social insurance authorities.
- Frequency: Twice a year, including periods with no recent hire or departure.
- Deadline: Before 5 June for the six-month report and before 5 December for the annual report.
- Files to submit: Electronic Form 01/PLI under Decree 145/2020/ND-CP, as implemented through Decree 129/2025/ND-CP.
- Owner check: Reconcile headcount, employment status and contract data with payroll records before filing.
4. Corporate Income Tax provisional payment
- Definition: A company generally pays provisional Corporate Income Tax, or thuế TNDN tạm nộp, each quarter and finalizes CIT annually.
- Key point: For ordinary business income, this is normally a payment obligation, not a quarterly CIT return. Special activities may require separate forms.
- Deadline: The last day of the first month after each quarter. Total provisional CIT for all four quarters must generally reach at least 80 percent of the annual CIT liability. Late-payment interest can apply to a shortfall.
- Files to submit: No standard quarterly return for ordinary business income. Use the electronic state-budget payment document generated through the tax or banking system.
- Owner check: Update the full-year forecast before Q4 closes, including non-deductible expenses and tax adjustments.
5. The year-end filing package
For a calendar-year company, the following items should be managed as one closing project.
Annual financial statements
- Definition: The statements present the company's financial position, results and explanatory notes under the applicable Vietnamese accounting regime.
- Deadline: Within 90 days after the financial year ends, normally 31 March for a calendar-year company.
- Files to submit: The applicable financial-statement set, generally including the statement of financial position, income statement, cash flow statement where required, and notes.
- Owner check: Reconcile banks, receivables, fixed assets, payroll, tax and related-party balances.
Annual CIT finalization
- Definition: The finalization converts accounting profit into taxable profit and reconciles final CIT with provisional payments.
- Deadline: The last day of the third month after the tax year ends, normally 31 March.
- Files to submit: Electronic Form 03/TNDN with the applicable schedules for matters such as losses, incentives, overseas tax or tax allocation.
- Owner check: Review deductions, related-party transactions, foreign contractor tax and incentives.
Annual PIT finalization by the company
- Definition: The company, as the income-paying organization, reconciles salaries, PIT withheld and amounts finalized for employees who validly authorize it to act on their behalf.
- Deadline: The last day of the third month after year-end, normally 31 March. A company that made no salary or wage payments during the year is not required to file this finalization.
- Files to submit: Electronic Form 05/QTT-TNCN with Forms 05-1/BK-QTT-TNCN, 05-2/BK-QTT-TNCN and 05-3/BK-QTT-TNCN as applicable. Retain Form 08/UQ-QTT-TNCN authorizations.
- Owner check: Separate leavers and multiple-income cases, and reconcile annual payroll with quarterly returns.
6. Independent audit report, if required
- Definition: An independent audit is a licensed auditor's opinion on the annual financial statements. A small company or startup is not automatically subject to statutory audit merely because of its size or legal form.
- Scope: Mandatory audit applies to categories specified by law, including foreign-invested enterprises, credit institutions, financial and insurance businesses, public companies, issuers, securities businesses, state-owned enterprises and certain state-funded entities or projects.
- Timing: Complete the audit in time to attach the auditor's report to the annual financial statements.
- Files to submit: Audited financial statements and the signed independent auditor's report, commonly attached as PDF where the filing system permits.
- Owner check: Appoint the auditor early and prepare balances, confirmations, contracts, payroll and tax files. See our Annual Audit in Vietnam 2026 guide for more detail.
7. Large workforce change notification: the 50-employee threshold
- Definition: This notice informs the public employment service organization of a significant increase or reduction in headcount.
- Trigger: From 1 January 2026, the separate notice is required when the workforce increases or decreases by at least 50 employees. Smaller changes do not trigger this form, but they must still be reflected in the recurring labour report where applicable.
- Deadline: Decree 374/2025/ND-CP does not set a fixed monthly date. Submit promptly when the threshold is reached.
- Files to submit: Form 33 issued with Decree 374/2025/ND-CP.
- Owner check: Document the threshold calculation and confirm the current submission channel with the local public employment service organization.
Where to submit the reports
Most filings in this checklist are electronic and require the company's VNEID account plus a valid digital signature. VAT returns, quarterly PIT withholding returns, annual CIT finalization, annual PIT finalization by the company and annual financial statements can be filed through the Tax Department's Public Service Portal. Social insurance increase and reduction dossiers can be filed through the Vietnam Social Security Public Service Portal or an authorised I-VAN provider.
For ordinary business income, remember that quarterly provisional CIT is generally an electronic payment rather than a separate return. Our Vietnam eTax for Businesses guide provides a practical overview of portal access and tax filing.
A baseline, not the whole calendar
Additional obligations can arise from ownership, licences, employees, transactions and industry. Examples include investment-project reports, foreign contractor tax, transfer-pricing disclosures, foreign-worker reports, statistics and environmental filings.
At the start of each month, ask your accountant what is due, what new event triggered an extra filing, who will review and sign it, and where the official acceptance notice is stored. That short routine keeps compliance visible without asking the founder to become the accountant.
Confirm your calendar with a qualified accountant, tax adviser or lawyer. If you need support, contact Easytiger and we can connect you with a suitable professional in Vietnam.
This article is for general information only and does not constitute legal, tax or accounting advice.

 Business & Tax
 Business & Tax
 Business & Tax