Vietnam Social Insurance (BHXH) in 2026: Everything You Should Know Before It Surprises You
Kylie NguyenCo-founder at Easytiger.vn · July 28, 2026 · 15 min read
Making sense of the 2026 BHXH reforms: A straightforward guide for expats and businesses building a future in Vietnam. (This article was originally published on 01 Apr 2026 on our substack and modified on 28 Jul 2026)
You signed a contract, you started working, and then someone mentions BHXH. Or maybe your company sends you a payslip with deductions you did not expect. Or you are leaving Vietnam and someone at the office says you can claim a lump sum from your social insurance, but nobody knows how.
If any of that sounds familiar, this guide is for you. Vietnam’s social insurance system has gone through major reforms as of July 1, 2025, and there is more at stake here than a line item on your payslip. Done right, part of it is actually money you can get back, and a safety net you are building while you work.
What Is Social Insurance in Vietnam, and Who Manages It?
Social insurance in Vietnam, locally known as Bảo Hiểm Xã Hội or BHXH, is a mandatory government-managed system where both employers and employees contribute a percentage of salary into a national fund. That fund then pays out when life takes an unexpected turn: illness, maternity leave, workplace accidents, retirement, or the death of a breadwinner.
The system is managed by Vietnam Social Security (VSS), which has operated under the Ministry of Finance since March 1, 2025, following a governmental restructuring. VSS oversees contribution collection, benefit processing, and nationwide distribution.
There are three components under the mandatory social insurance umbrella:
Social Insurance (SI / BHXH): covers sickness, maternity, occupational accidents, retirement, and survivorship benefits. Applies to Vietnamese employees on contracts of 1 month or more and foreign employees on contracts of 12 months or more.
Health Insurance (HI / BHYT): covers medical examinations and inpatient/outpatient treatment. Applies to Vietnamese employees on contracts of 1 month or more and foreign employees on contracts of 12 months or more.
Unemployment Insurance (UI / BHTN): provides income support during job loss, plus job placement support. Applies to Vietnamese employees only, on contracts of 1 month or more (from January 1, 2026). Foreign employees do not contribute to this fund.
Where can you check your records?
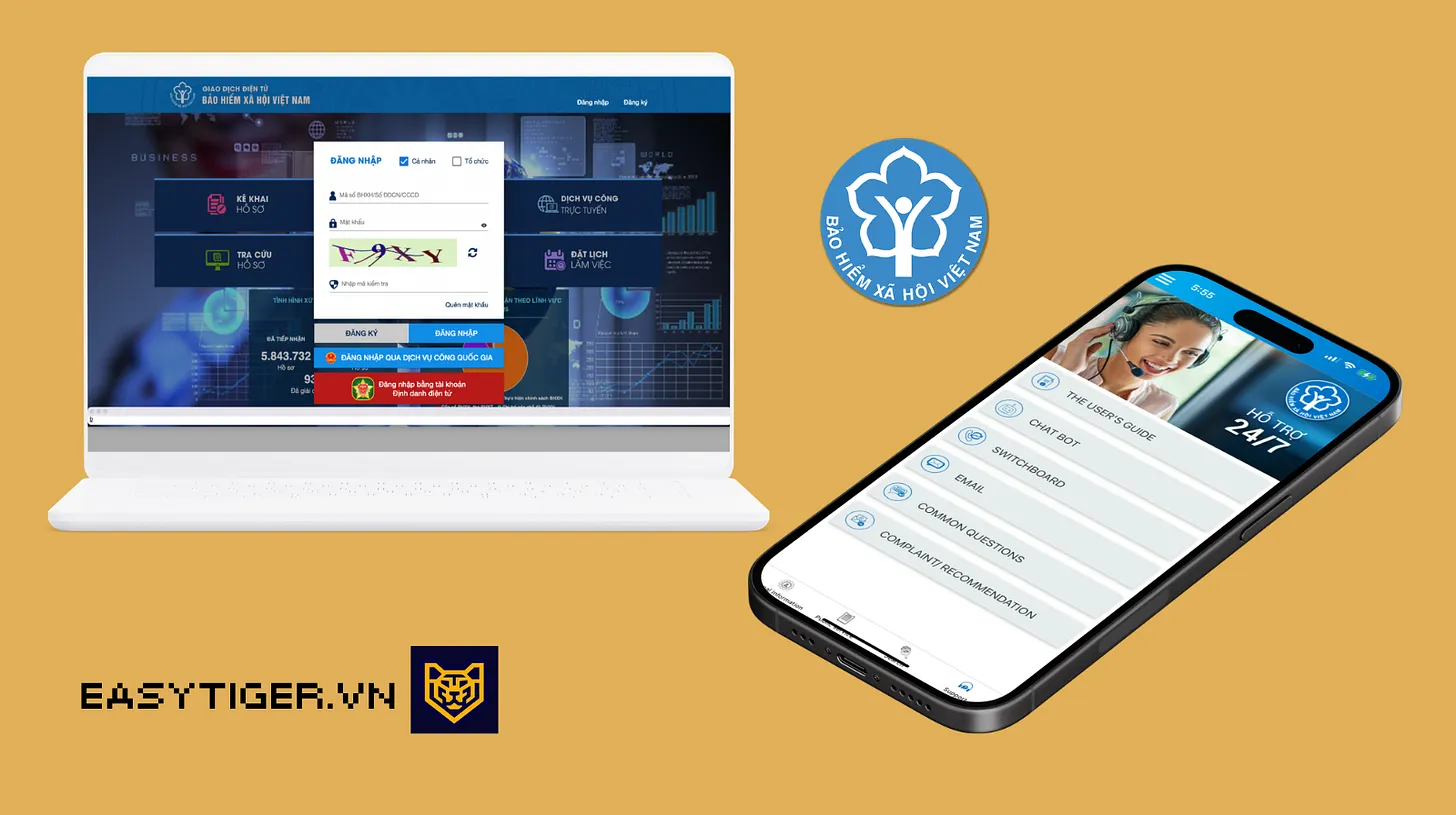
The VssID app (available on iOS and Android) is the official Vietnam Social Security mobile app. It lets you look up contribution history, access your digital health insurance card (BHYT), and track your accumulated months. Since 2023, it can be accessed through your VNeID electronic identity account, so there is no separate login to manage. You can also look things up via the web portal at vss.gov.vn using your citizen ID or passport number. As of August 2025, VSS has unified social insurance codes with citizen ID numbers, making records easier to trace.
Why Does This Actually Matter? The Part Most People Skip
For many expats and foreign workers, BHXH feels like just another deduction. But that framing misses the point entirely.
First, the practical reality: your social insurance contributions are not simply money gone. When your labor contract ends or your work permit expires without renewal, a foreign employee can claim a one-time lump sum worth 2 months of average insured salary for each year of contributions. It is not a refund of everything you and your employer paid in, but for someone on a mid-range salary working in Vietnam for two to three years, that can still translate to tens of millions of dong paid back to you when you leave, money that was quietly building while you worked.
Second, if you stay long enough, you are building toward real retirement benefits. Foreign workers who reach 15 years of social insurance contributions in Vietnam are eligible for a monthly pension. For women, it starts at 45% of average monthly insured salary at 15 years. For men, it starts at 40% at 15 years and rises by 1% a year to 45% at 20 years. Each further year then adds 2%, up to a maximum of 75%. For anyone considering a long-term future here, that is not a trivial benefit.
Third, the system covers you while you are here. Vietnamese public hospitals operate on the health insurance system. With an active BHYT card (health insurance card), you can access inpatient and outpatient care at public facilities with 80 to 100% coverage depending on conditions. For the sick leave benefit, if you are certified ill by a licensed medical provider, you can receive 75 to 100% of your monthly salary during leave. Maternity benefits are also substantial, with female employees entitled to 6 months of paid maternity leave calculated at 100% of their average insured salary, and male employees now entitled to 5 to 14 days of paternity leave under the 2025 reforms.
To be straightforward about it: public hospitals in Vietnam are not always the most comfortable experience, and not everyone will choose to use them. But having that health insurance card (BHYT) still means you have access to covered care when you genuinely need it, and that is a lot better than facing a hospital bill with no coverage at all.
In short: social insurance is not just a compliance box to tick. It is a financial tool that rewards participation.
How Much Do You Pay? Contribution Rates Explained
How are these numbers actually figured out? It all starts with something called the insured salary, which is the figure that the contribution percentages are applied to, and it does not always match what you see on your payslip.
By law, the insured salary includes the base salary stated in your labor contract, plus any fixed, regular allowances or supplements with specific amounts written into that contract. However, variable welfare perks that are listed separately as benefits rather than salary components (such as meal, phone, or transport allowances provided outside the contract structure) do not count toward the contribution base. Because of these exclusions, the insured salary is usually just the base salary component of your contract.
In the real world, companies often establish a benchmark for social insurance contributions. While some firms contribute based on your full gross salary, many choose to set a specific benchmark, such as 80% of your gross salary, or stick closer to the legal minimums.
There are strict guardrails on this:
The floor: You cannot contribute on an insured salary lower than the applicable regional minimum wage for employees.
Regional minimum wages — effective January 1, 2026
Region
Monthly minimum
Key areas
Region 1
5,310,000 VND ~USD 204
Urban Hanoi, Ho Chi Minh City, Hai Phong, Da Nang and key industrial hubs
Region 2
4,730,000 VND ~USD 182
Peri-urban Hanoi and HCMC, most of Binh Duong, Dong Nai, Can Tho
Region 3
4,140,000 VND ~USD 159
Provincial cities and industrial towns; parts of Hai Duong, Khanh Hoa, Long An
Region 4
3,700,000 VND ~USD 142
Remaining rural provinces and districts
Per Decree 293/2025/ND-CP. These figures are the floor for social insurance contribution bases. A company cannot set an insured salary below the rate for its operating region.
The ceiling: There is a cap of 20 times the government reference level. As of 1/7/2026, the government reference level is VND 2,530,000/month, putting the maximum insured salary cap at VND 50,600,000/month. Anything earned above that ceiling is not subject to additional social insurance contributions.
Contribution Breakdown
For Vietnamese employees and their employers:
Contribution type
Employee
Employer
Social Insurance (BHXH)
8%
17.50%
Health Insurance (BHYT)
1.50%
3%
Unemployment Insurance (BHTN)
1%
1%
Total
10.50%
21.50%
Unemployment insurance applies to Vietnamese employees on contracts of 1 month or more (from January 1, 2026). Social and health insurance contributions are based on the insured salary, floored at the applicable regional minimum wage and capped at VND 50,600,000/month. Unemployment insurance has its own cap of 20 times the applicable regional minimum wage.
For foreign employees and their employers:
Foreign employees contribute to SI and HI but are excluded from unemployment insurance.
Contribution type
Employee
Employer
Social Insurance (BHXH)
8%
17.50%
Health Insurance (BHYT)
1.50%
3%
Total
9.50%
20.50%
Foreign employees are excluded from unemployment insurance, making the combined rate 30% versus 32% for Vietnamese employees. The employer’s 17.5% social insurance share, for Vietnamese and foreign employees alike, already includes 0.5% for the work accident and occupational disease fund. Applies to foreign workers on fixed-term labor contracts of 12 months or more with an employer in Vietnam. Source: Social Insurance Law 2024 and Decree 158/2025/ND-CP.
A Real Example: What It Looks Like in Practice
Imagine a local employee with a contracted gross salary of VND 25,000,000 per month. Depending on the company’s internal payroll strategy, the actual insured salary used for contributions can vary significantly.
Example 1: The legal floor (regional minimum wage)
Some companies choose to set the insured salary at the absolute minimum permitted by law to minimize monthly costs. For a business based in a Region 1 urban area such as Ho Chi Minh City or Hanoi, the 2026 minimum wage is VND 5,310,000.
Employee pays (10.5%): VND 557,550
Employer pays (21.5%): VND 1,141,650
Total monthly social insurance contribution: VND 1,699,200
Example 2: The 80% salary benchmark
Other companies take a more balanced approach, setting the contribution benchmark at 80% of the gross salary. In this case, the insured salary becomes VND 20,000,000.
Employee pays (10.5%): VND 2,100,000
Employer pays (21.5%): VND 4,300,000
Total monthly social insurance contribution: VND 6,400,000
From a business perspective, the employer-side contribution represents a significant portion of the total cost of each hire, well beyond the base salary listed in the contract.
Who Is Required to Participate, and When?
Employers must register employees within 30 days of their start date. Under the Social Insurance Law 2024, the SI book must be issued within 5 working days of a complete application. Late payment carries a daily interest charge of 0.03% on the outstanding amount, and deliberate evasion can result in administrative prosecution.
For foreign employees specifically, mandatory social insurance participation applies when both conditions are met:
The labor contract is for a fixed term of 12 months or more with an employer in Vietnam.
The employee has not yet reached retirement age at the time of signing (in 2026, 61 years and 6 months for men and 57 for women, rising gradually until men reach 62 in 2028 and women reach 60 in 2035).
Foreigners are not required to join if they are:
Intra-company transferees (managers, directors, experts, or technical workers assigned from a foreign parent company, where the foreign company has employed them for at least 12 consecutive months beforehand).
At or beyond retirement age at the time of contract signing.
Covered under a bilateral social insurance treaty with Vietnam. The Vietnam-South Korea SI agreement is in effect as of January 1, 2024.
Something many business owners miss: unpaid company executives are still required to contribute.
Before July 1, 2025, only managers with a labor contract and an actual salary were required to participate in social insurance. The Social Insurance Law 2024 changed that. Now, even if you hold a management title and draw no salary from the company, the obligation still applies to you.
Specifically, the new rules cover directors, general directors, board members, members of the supervisory board, capital representatives, and other elected management roles across all company types and structures, not just single-member LLCs. The law refers to these individuals as enterprise managers without a salary (người quản lý doanh nghiệp không hưởng tiền lương), and they are now a named category of mandatory social insurance participant under Article 2 of the Social Insurance Law 2024. If you are a Vietnamese citizen, your name appears on the company registration documents in a management capacity, and you have not yet reached retirement age, you are in. This category applies to Vietnamese citizens only, not to foreign employees.
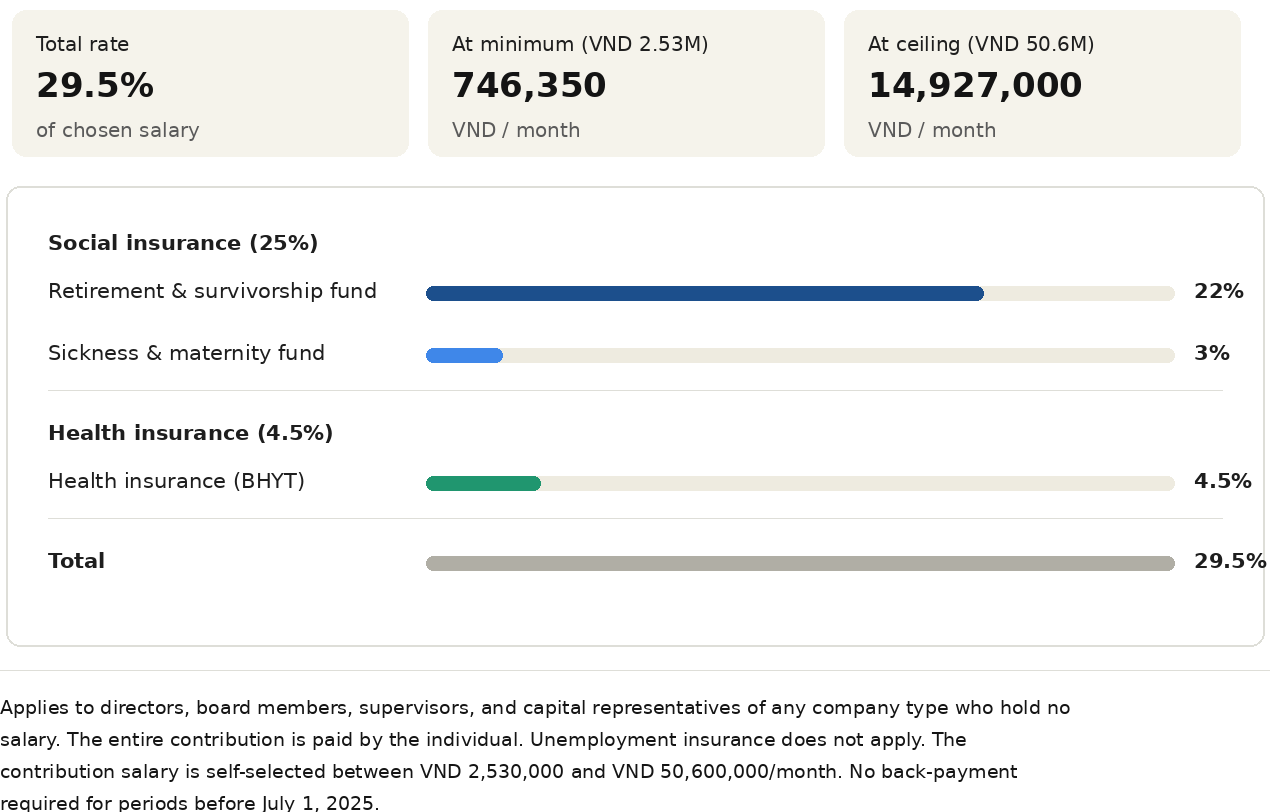
For unpaid executives, the entire social insurance contribution falls on the individual rather than being split with the company. The total rate is 25% of the chosen contribution salary (3% into the sickness and maternity fund, 22% into the retirement and survivorship fund), plus 4.5% for health insurance, bringing the combined total to 29.5%. The contribution salary is self-selected within a range from VND 2,530,000/month at the minimum up to VND 50,600,000/month at the maximum (as of 1/7/2026). To put that in concrete terms: someone choosing the minimum reference level would pay roughly VND 746,350/month, while someone contributing on a higher self-declared salary would pay proportionally more. Payment can be made monthly, quarterly, or every six months.
There is no back-payment required for periods before July 1, 2025, but the obligation applies from that date forward. If a director holds positions at multiple companies, social insurance is only required at the first company where they manage or administer. Unemployment insurance does not apply to this group.
Withdrawing Social Insurance: What Locals and Foreigners Can Each Do
This section is where the rules diverge most, and where the 2025 reform changes things significantly.
For Vietnamese employees:
The lump-sum withdrawal option has tightened considerably under the Social Insurance Law 2024. Employees who began contributing before July 1, 2025 still have access to some one-time withdrawal conditions, though with more restrictions than before. For those who join the system after July 1, 2025, a lump-sum payout is only available in specific circumstances: reaching retirement age without meeting the 15-year threshold, being diagnosed with a serious qualifying illness (cancer, paralysis, decompensated cirrhosis, severe tuberculosis, HIV/AIDS), or having a working capacity loss of 81% or more. The previously popular option to withdraw after simply being unemployed for 12 months no longer applies for new participants.
On the positive side, the minimum social insurance contribution period to qualify for a monthly retirement pension has been reduced from 20 years to 15 years from July 1, 2025, making long-term pension access significantly more achievable.
For foreign employees:
The rules are more straightforward and considerably more flexible. Foreign workers can apply for a one-time lump-sum withdrawal when any of the following apply:
The labor contract ends, or the work permit/license expires without renewal.
Retirement age is reached but fewer than 15 years of contributions have been made.
A qualifying serious illness is diagnosed (such as cancer, paralysis, decompensated cirrhosis, severe tuberculosis, or AIDS).
Work capacity loss of 81% or more, or a very severe disability.
The employee is eligible for a pension but no longer lives in Vietnam.
How the payout is calculated:
Claimed amount = 2 x average monthly insured salary x number of years contributing to SI. For contributions under one year, the amount equals total paid contributions, capped at two months of average insured salary.
Example: If a foreign employee has an average monthly insured salary of VND 20,000,000 and contributes for 3 years, the calculation is: 2 x VND 20,000,000 x 3 = VND 120,000,000 (approximately USD 4,800).
To claim, submit Form 14-HSB to your social insurance office at least 30 days before your contract expires. Processing takes within 10 working days.
One thing to be aware of: if you claim your lump sum and then return to work in Vietnam shortly afterward, the Social Insurance authority may demand repayment of the withdrawn amount, and administrative penalties can apply. This is confirmed under the current Social Insurance Law 2024 framework and Decree 158/2025/ND-CP. Plan your timing carefully if there is any chance you will return.
What You Should Keep in Mind
Social insurance is one of those things that is easy to ignore until something goes wrong. Here is what is worth staying on top of:
Register on time. The 30-day window from an employee’s start date is strict. Employers who miss it face back-payment obligations plus daily interest penalties.
Know your contribution base. Make sure you understand the difference between base salary and separately listed welfare benefits. The line between the two matters when negotiating salary packages, setting up payroll, or simply verifying that what you are being told on paper matches what is actually being contributed on your behalf.
Foreigners are not exempt by default. If a foreign employee has a fixed-term labor contract of 12 months or more with an employer in Vietnam, they are in unless one of the exemptions above applies. Review each contract individually, especially for roles that were onboarded informally.
When you leave a job, collect your documentation before you go. Whether switching employers or leaving the country, always request your social insurance contribution record and book confirmation from HR before your last day. This document is your proof of how many months you have contributed, and it directly affects both your withdrawal amount and any future unemployment insurance claims. For Vietnamese employees, this record is a required document when filing for unemployment benefits at the employment center.
Use the digital tools. The VssID app and VNeID integration mean you can verify your own social insurance contribution history without depending on HR. This matters especially when onboarding with a new employer, as gaps or errors in past contributions are your responsibility to catch.
Bilateral treaties may apply. Vietnam has a bilateral social insurance agreement with South Korea (effective January 1, 2024). Other agreements may be in progress. If your employees are nationals of a country with an active treaty, they may qualify for exemption or credit, so it is worth checking before onboarding.
This article is for informational purposes only and does not constitute legal, HR, or tax advice. Social insurance regulations in Vietnam are subject to change. Contribution rates, eligibility rules, and withdrawal conditions referenced in this article are based on the Social Insurance Law 2024 and related decrees effective as of the date of publication. For guidance specific to your business or personal situation, consult a qualified specialist.
Frequently asked questions
Yes, in most cases. Under Article 2(2) of the Law on Social Insurance No. 41/2024/QH15, in force since 1 July 2025, a foreign citizen must join compulsory social insurance when working under a fixed-term labor contract of 12 months or more with an employer in Vietnam. The same 12-month rule applies to compulsory health insurance under the amended Law on Health Insurance No. 51/2024/QH15. Exemptions exist for intra-company transferees, people at retirement age when signing, and cases covered by an international treaty.
Three groups are exempt under Article 2(2) of the Law on Social Insurance No. 41/2024/QH15: intra-company transferees, people who had already reached statutory retirement age when the labor contract was signed, and cases where an international treaty Vietnam has joined provides otherwise. Under Decree 219/2025/ND-CP, an intra-company transferee must have been employed by the foreign enterprise for at least 12 consecutive months before coming to Vietnam. In 2026 the retirement age is 61 years 6 months for men and 57 for women.
The employee pays 9.5% and the employer 20.5% of the contribution salary, 30% in total. The employee's share is 8% to the retirement and survivorship fund plus 1.5% health insurance, and the employer's share is 14% retirement and survivorship, 3% sickness and maternity, 0.5% occupational accident and disease, and 3% health insurance. The rates come from the Law on Social Insurance No. 41/2024/QH15, Decree 158/2025/ND-CP and Decree 188/2025/ND-CP; eligible employers may pay 0.3% instead of 0.5% for occupational accidents.
No. Since 1 January 2026, unemployment insurance is governed by the Law on Employment No. 74/2025/QH15, which defines an employee as a Vietnamese citizen aged 15 or over, so neither foreign employees nor their employers contribute to the unemployment insurance fund for them. Foreign employees on fixed-term contracts of 12 months or more still pay compulsory social insurance and health insurance.
VND 50,600,000/month from 1 July 2026. The Law on Social Insurance No. 41/2024/QH15 caps the contribution salary at 20 times the reference level, which equals the base salary while the base salary exists, and Decree 161/2026/ND-CP raised the base salary from VND 2,340,000 to VND 2,530,000/month from 1 July 2026. Before that date the cap was VND 46,800,000/month. Salary above the cap attracts no further compulsory social insurance contributions.
Yes, once contributions have stopped and the employee applies. Under Article 70(2) of the Law on Social Insurance No. 41/2024/QH15, a foreign employee qualifies when the labor contract ends or the work permit, practicing certificate or license expires without renewal; on reaching retirement age with under 15 years of contributions; with cancer, paralysis, decompensated cirrhosis, severe tuberculosis or AIDS; with a work capacity loss of 81% or more or a very severe disability; or when eligible for a pension but no longer living in Vietnam.
It equals 2 months of average monthly contribution salary for each year of contributions from 2014 onward, under Article 70(3) of the Law on Social Insurance No. 41/2024/QH15, with past salaries adjusted for consumer price inflation. If contributions total less than one year, the payment equals the amount contributed, capped at 2 months of average salary. It is not a refund of everything the employee and employer paid in. For example, an average of VND 20,000,000 over 3 years gives about VND 120,000,000.
Yes, with at least 15 years of compulsory social insurance contributions and on reaching retirement age, under Article 64 of the Law on Social Insurance No. 41/2024/QH15, which covers foreign employees. Women receive 45% of average contribution salary at 15 years; men receive 40% at 15 years, rising 1% a year to 45% at 20 years. Each further year adds 2%, up to 75%. In 2026 the retirement age is 61 years 6 months for men and 57 for women.
Share article
Easytiger Match
Find the right professional
1Tell us what you need
2We shortlist professional(s) and introduce them to you